 5,717,360Compared with 5,467,105
Edition One
Bankside Insights
Introduction
Nicole Gordon
Better Bankside CEO
How is Bankside performing?
How healthy is the economic ecosystem in this part of London?
The national and global picture is quite frankly cheerless and Bankside is not an island. Better Bankside is invested in understanding the unique conditions of our neighbourhood.
This is the first of BB’s new insights reports which we will be publishing quarterly, capturing hyperlocal data and intelligence.
As much as statistics can be fascinating, local knowledge can be equally valuable intel. These reports will aim to tell the stories behind the data, combined with insights garnered through our connections across the area and position as custodian of the neighbourhood.
The data presented is just a snapshot of what we have access to, so if there is additional information that would be useful to your business we’d love to hear from you.
What is changing
Development Pipeline
Bankside continues to attract significant investment, enabling a strong and diverse development pipeline over the next five years. Our core analysis of the 25 current schemes making an impact are set out below.
10m+sqft new and repurposed floorspace delivered over next 5 years
25schemes surveyed
c40,000workers accommodated within the commercial floorspace
£100mestimated annual worker spend for Bankside
Potential impact
What this could mean for Bankside
01
More customers, more spend
Proposed commercial floorspace alone can accommodate c40,000 workers, worth a potential £100m worker spend per year for Bankside.
02
Diverse floorspace continues
Bankside’s commercial floor space still remains the highest quantum of development, however there has also been a significant increase in student accommodation and high end hotel beds across the BID area.
03
New homes
2,424 new homes are being proposed or delivered across the 25 schemes, however only around 27% of the proposed homes are classed as affordable. The total 2,424 homes proposed is still well below historic targets and housing remains a significant delivery challenge for Bankside.
04
The Low Line
175,000 sqft of railway arch redevelopment is being delivered by several of the major schemes in our survey. This proposed redevelopment could attract major new cultural and leisure use as well as continuing the tradition of the arches supporting much more diverse and local uses.
The Opportunity
Bankside is experiencing continued development growth in established markets such as office and commercial but also in some newer emerging sectors such as student accommodation and higher end hotels. Away from major development, the railway arches along the Low Line continue to provide Bankside with a uniquely diverse and much more local offering including makers, sellers and after work destinations. New homes mean more people seeking out a neighbourhood to service their everyday and their leisure time, whilst tourists and visitors will have more choice on where to stay. Over the next five years footfall is likely to both increase and diversify with spending patterns also following this trend.
Better Bankside regularly reviews the Bankside development pipeline and its impact on the area. Visit Developments shaping Bankside (https://betterbankside.co.uk/what-we-do/developments-shaping-bankside/) for more information.
Local intelligence
Bankside Voices
There is much media speculation, often conflicting, on the property landscape in London and the UK. USP are commercial property experts, born and based in Bankside, and BB’s go-to for intel on how the SE1 market is performing.
We asked Ben Fisher, Managing Partner at USP, for the inside track…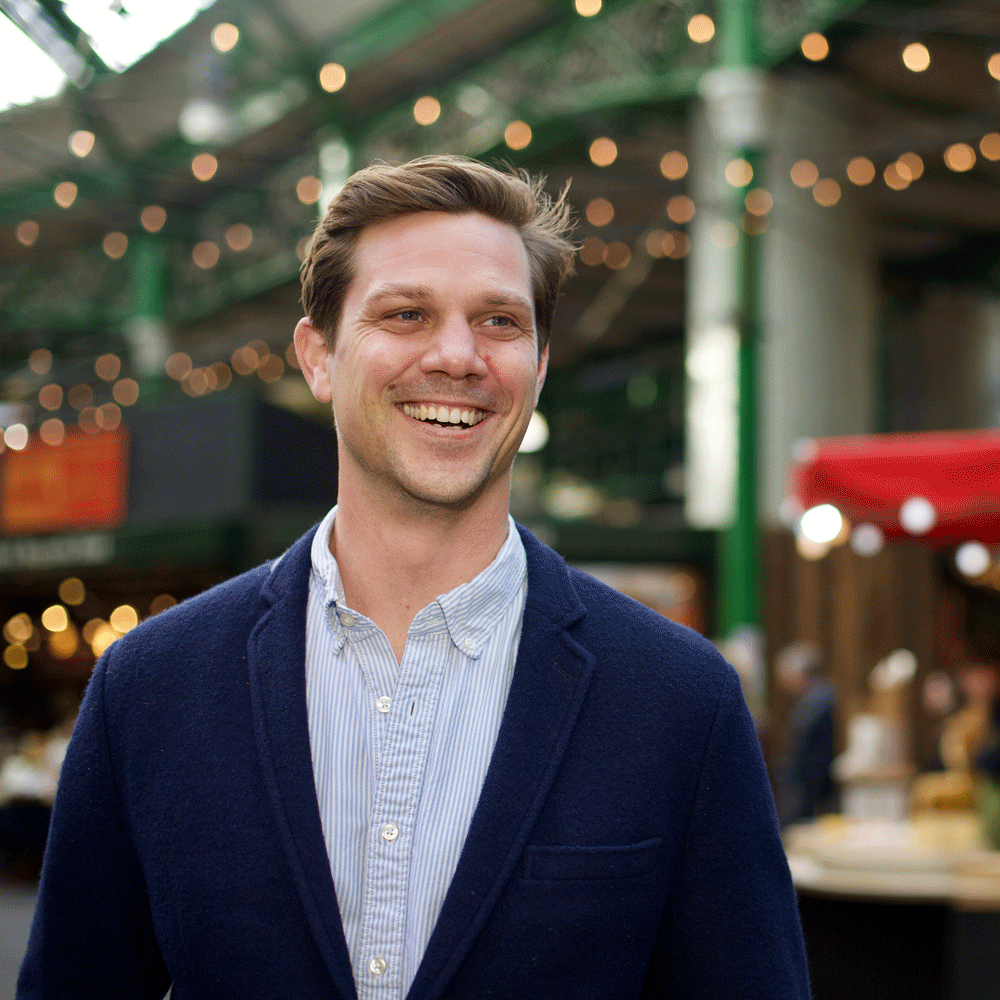
Ben FisherManaging Partner, USP
Bankside is increasingly seen as a core London office destination with strong demand for commercial space. Q1 2026 saw the highest volume of space let in a single quarter since Q2 2017. This is driven by the best space currently available. However a clear split between top-tier and lower-tier spaces continues. Whilst fewer units are sitting empty and rents are rising for prime space, older or lower quality space continues to lag.
High profile activity such as BP taking c.200,000 sq ft at Timber Square helps to raise the area’s profile and attract investment.
The conversation continues
Q&A with Ben Fisher
We asked Ben what he is seeing in the market now, and what may lie ahead for Bankside.
What trends are you seeing?
The Bankside market has traditionally attracted a very diverse mix of occupiers owing to its price point, proximity to prime transport links, wide range of local amenities and vibrant cultural attractions and not forgetting the access to the River Thames and other peaceful pockets of open space.
Post-Covid we were seeing more homegrown moves, businesses relocating within the area, but that is shifting back to a larger proportion of businesses moving in from other parts of London.
We’re seeing an increase in demand for building features such as communal club rooms, roof terraces and a strong entrance experience.
Prime rents for this part of London are £79.50 per sq ft, however the riverside premium buildings are achieving an average of £130 per sq ft once you combine the rents across all the space in those buildings.
Any predictions for the year ahead?
We anticipate a similar take up level to last year provided there is economic stability. London is a very mature market and is the envy of many a city owing to its draw on talent and global business identity. This identity is starting to wane and can only be retained with a government that supports business.
From a developer point of view finding large enough sites that meet occupier demand is now proving challenging. However developers of smaller schemes need to have more belief in the market to fill the coming shortage of space.
Bankside has always been at the vanguard of change, whilst also boasting a heritage to be proud of. There is a strong pipeline of high quality developments that will bring further modernity to the neighbourhood. Bankside’s future can build on the strength of its established market, provided it stays true to its core strengths of creativity, innovation and culture.
Footfall and spend in Bankside are key indicators of how the neighbourhood is performing.
There is a trend for stability of footfall and increasing spend in Bankside post 2022.
Early summer is an important quarter for spending and footfall in Bankside as tourist numbers increase and warmer, longer days encourage workers and visitors to make the most of our amenities and public spaces.
Relative spend has increased over 2023–2026 against a slight downward trend in comparable areas.
The likely explanation for this is two-fold. More opportunities to spend and sector mix. Bankside has seen year on year growth from 2016 onwards in amenities such as restaurants, bars, cafes. Bankside’s higher proportion of businesses in hospitality and leisure sectors, and relatively lower levels of retail, means the area is more exposed to hospitality-led spending, which has held up better than retail-led districts.
Summer quarter (July to September) is the strongest on average for spend as Bankside benefits from tourists and workers making the most of our excellent offer.
Spending takes a downward turn in the first quarter of each year (January to March).
Tell us what information will help you and your business – we’re here for you.
Definition
Footfall
For footfall, BT footfall data derives from anonymised and aggregated mobile phone signals present in an area for at least 10 minutes. It captures signal data from both domestic and international phones. This allows BT to show how many people.
Definition
Spend
Spend data is supplied by Mastercard. It is not a pound figure. It is an indicative figure showing increase and decrease from a baseline set in 2018 when the data started being recorded. It comes from in-person spending on Mastercard-branded debit and credit cards, extrapolated based on Mastercard market share.
Supporting data snapshot1 April – 30 June 2026
5,717,360Compared with 5,467,105 1,612,203Compared with 1,559,598
 50,225Compared with 48,555
 21,338Compared with 19,964
 11,024Compared with 10,821
 6,692Compared with 6,249
Footfall and spend
A week in Bankside
Footfall is strongest on Thursdays, while spend peaks on Saturday. The supplied quarterly graphs show the different rhythms of workers and visitors across the week.
Quarterly pattern
Average footfall by day
1 April – 30 June 2026
Highest dayThu
Average footfall
Source: BT Location Insights
Quarterly pattern
Average spend (index) by day
1 April – 30 June 2026
Highest daySat
Average spend (index)
Source: Mastercard GeoInsights
The wider pattern
Trends
The supplied historic series provide wider context, showing footfall and spend over longer periods.
Footfall 2022 – 2026
Series low1,219,730Series high2,323,605
Y-axisFootfall (people)
Sep 2022Apr 2023Sep 2023Apr 2024Sep 2024Apr 2025Sep 2025Apr 2026
Source: BT Location Insights
Footfall July 2024 – June 2026
Series low1,786,945Series high2,323,605
Y-axisFootfall (people)
Sep 2024Apr 2025Sep 2025Apr 2026
Source: BT Location Insights
Spend January 2018 – June 2026
Series low1,406Series high26,157
Y-axisMastercard spend index (not £)
Apr 2018Sep 2018Apr 2019Sep 2019Apr 2020Sep 2020Apr 2021Sep 2021Apr 2022Sep 2022Apr 2023Sep 2023Apr 2024Sep 2024Apr 2025Sep 2025Apr 2026
Source: Mastercard GeoInsights
Spend July 2024 – June 2026
Series low10,748Series high19,877
Y-axisMastercard spend index (not £)
Sep 2023Apr 2024Sep 2024Apr 2025Sep 2025Apr 2026
Source: Mastercard GeoInsights
The data presented is just a snapshot of what we have access to, so if there is additional information that would be useful to your business we’d love to hear from you.